2026-10-20 · 5 min read · McKinney
What If Rates Don't Come Down? Buying a Home in McKinney
Waiting for a better rate sounds smart
I hear this question almost every week. "Should we buy now, or wait for rates to come down?" It is a fair question. On October 8, the average 30-year mortgage rate was 7.40%, according to Freddie Mac. A year ago it was 6.30%. Rates had gone up seven weeks in a row.
So waiting sounds smart. Before you decide on a McKinney home, let's look at what waiting actually gets you.
This is a three-part series, Buy Now or Wait? Part 1: what if rates don't come down. Part 2: do you need a home now. Part 3: taxes, homestead and equity.
FOMO works in both directions
In 2021 and 2022, fear of missing out ran this market. Buyers waived inspections, wrote offers far over asking, and bought the first house that would take them. Collin County home prices jumped 24% in 2022 alone. Some of those buyers paid the top of the market.
Today the fear runs the other way. Buyers are afraid of locking in at 7.4% and then watching rates drop. Sellers are afraid of selling for less than their neighbor got in 2022.
Both fears do the same thing. They make you decide based on a headline instead of your own numbers. FOMO is a feeling, not a plan.
Nobody can time it, including the experts
You have probably heard you cannot time the stock market. The same is true in real estate. Here is proof from the people whose whole job is predicting rates.
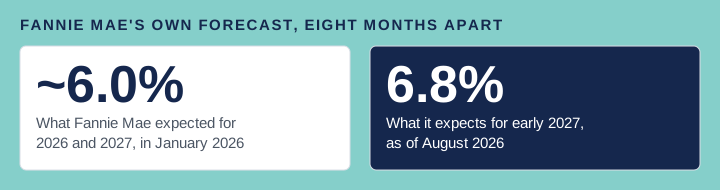
An energy shock overseas pushed inflation and bond yields up, and the forecast moved most of a point. The Mortgage Bankers Association now expects about 6.7% through 2027.
If the pros missed by that much in eight months, nobody can tell you the month to buy. Not me, not your brother-in-law, and not the internet.
The math on waiting a year
Take a $500,000 home in McKinney with 10% down, so a $450,000 loan. Here is the monthly principal and interest under four futures. Taxes and insurance are left out so the comparison stays clean.
| If you… | Price | Rate | Payment |
|---|---|---|---|
| Buy today | $500,000 | 7.40% | $3,116 |
| Wait a year, rates fall, prices stay flat | $500,000 | 6.70% | $2,904 |
| Wait a year, rates fall, prices rise 4.4% | $522,000 | 6.70% | $3,032 |
| Wait a year, rates stay, prices rise 4.4% | $522,000 | 7.40% | $3,253 |
4.4% is Collin County's average yearly price growth over the last 30 years (see Part 2). 6.7% is roughly where the major forecasters expect rates in 2027.
The best case for waiting saves about $212 a month. If prices climb at their normal pace, the savings shrinks to about $84. If rates do not come down, waiting costs you about $137 a month for the life of the loan. And for that whole year, you are paying rent and building none of your own equity.
What if rates drop after you buy?
Then you look at a refinance. That is the safety valve, and it is a real one. Three things to know going in:
- It costs money. A refinance has closing costs, often several thousand dollars. The monthly savings has to pay those back within a few years to be worth it.
- You have to qualify again. Your income, credit, and the home's value all get checked a second time.
- It is not promised. Rates may not fall enough to make it pay. Plan as if you will keep today's rate.
Here's the move
Buy a payment you can live with at today's rate. If rates fall later, the refinance is a bonus, not the plan. If the payment only works once rates drop, it is not the right house yet.
Want your own numbers, not a sample house? Send me your price range and I will run all four futures with a lender I trust. You will get a straight answer, not a sales pitch.
Ask Terri or call me at 469-693-3839. You can also see how I help you buy, or start with buying a home in McKinney.
Sources and notes
Terri Egstad, Realtor®, Pinnacle Realty Advisors. Figures are current as of October 9, 2026. Payments are principal and interest only on a 30-year fixed loan. This post is general information, not financial, tax, or lending advice. Your rate depends on your credit, down payment, and loan type, so talk to a licensed lender before you decide.
Sources