2026-10-20 · 6 min read · McKinney
Taxes, Homestead, and the Money That Builds Quietly in McKinney
The part of the picture people skip
I once worked with a buyer who was scared about the money. We sat down with her lender and went through every cost, one at a time, until she could see she was in a good position. She closed on the home. I felt so proud of her.
Fear about money usually comes from not seeing the whole picture. So here is the part people skip when they buy in McKinney: what you get back for owning. This is Part 3 of the series, after Part 1 on rates and Part 2 on 50 years of prices.
Your homestead exemption: the biggest break most buyers miss
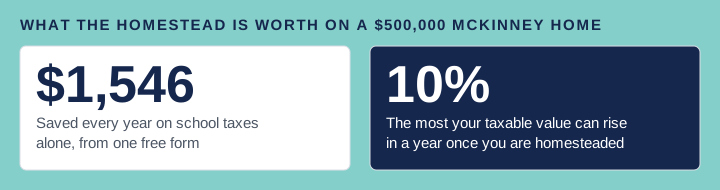
In Texas, your homestead is the home you own and live in. Filing for it is free, and it is worth more than most people realize.
- $140,000 off your school taxes. Texas voters raised the school homestead exemption from $100,000 to $140,000 in November 2025. School taxes are the biggest slice of your bill.
- $200,000 off if you are 65 or older, or disabled. A second amendment added another $60,000 for those homeowners. Their school taxes are also capped at the level of the year they qualify.
- A 10% cap on increases. After your first year, the taxable value of your homestead cannot go up more than 10% a year, even if the market jumps the way it did in 2022.
- You can file the year you buy. As soon as you own it and live in it, file with the Collin Central Appraisal District. No waiting until January.
- Protection from most creditors. The Texas Constitution protects your homestead from forced sale for most debts. The big exceptions are your mortgage and your property taxes.
The mortgage interest deduction: real, but smaller than you've heard
You can deduct the interest on up to $750,000 of mortgage debt, plus your property taxes. The catch is that it only helps if those add up to more than the standard deduction, which is $32,200 for married couples in 2026.
Here is how it plays out on a $500,000 McKinney home with a $450,000 loan at 7.40%:
| Mortgage interest, first year | $33,158 |
| Property taxes, after homestead | $7,189 |
| Total you could itemize | $40,347 |
| Standard deduction you would get anyway | $32,200 |
| Extra deduction from owning | $8,147 |
| Tax savings in the 22% bracket | about $1,800 a year |
Helpful, but not a reason to buy on its own. With a smaller loan or a lower rate, the benefit shrinks or disappears. Texas has no state income tax, so your property taxes are the main state and local tax you would deduct, well under the 2026 cap of $40,400.
When you sell, most of the gain is tax-free
If you have owned and lived in the home for at least two of the last five years, you can keep up to $250,000 of profit tax-free, or $500,000 for a married couple. For most families, that means the growth in your home's value is never taxed at all.
Equity builds while you live there
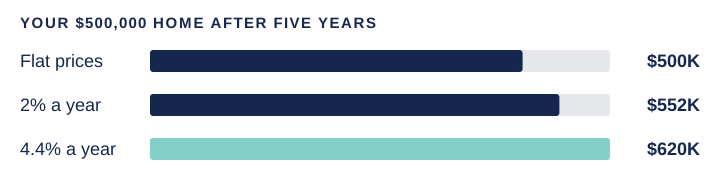
Every payment pays down a little of the loan. On that $450,000 loan at 7.40%, you would pay off about $24,600 of principal in the first five years. That is money you keep, even if prices do not move at all.
And if rates fall after you buy, you can look at refinancing to a lower payment, as long as the savings covers the cost. We covered that in Part 1.
Here's the move
File your homestead the week you move in. Then ask your CPA one question before you buy: "Will I itemize?" Count the homestead, the tax-free gain, and the equity. Treat any extra deduction as a bonus.
Want the whole picture for your situation? I will put you together with a lender and help you see every cost and every benefit before you decide. Clients first, always.
Ask Terri or call me at 469-693-3839. You can also see how I help you buy, or start with buying a home in McKinney.
Sources and notes
Terri Egstad, Realtor®, Pinnacle Realty Advisors. Tax figures are for the 2026 tax year and current as of October 9, 2026. The example assumes a married couple filing jointly with no other itemized deductions. Confirm anything that affects your taxes with a CPA, and your homestead with the Collin Central Appraisal District. This post is general information, not financial, tax, or lending advice. Your rate depends on your credit, down payment, and loan type, so talk to a licensed lender before you decide.
Sources
- CBS Texas: voters approve higher homestead exemptions (November 2025)
- MetroTex Association of Realtors: filing a homestead in the year you buy
- Collin Central Appraisal District
- Community Impact: McKinney FY 2025-26 tax rates
- Kiplinger: 2026 SALT deduction cap
- IRS Publication 936: Home Mortgage Interest Deduction
- IRS Publication 523: Selling Your Home